Identifying Underserved Manufacturing Clusters in Mid-Market Territories
Competitor moves faster when reps miss mid-market manufacturing clusters hiding in plain sight.
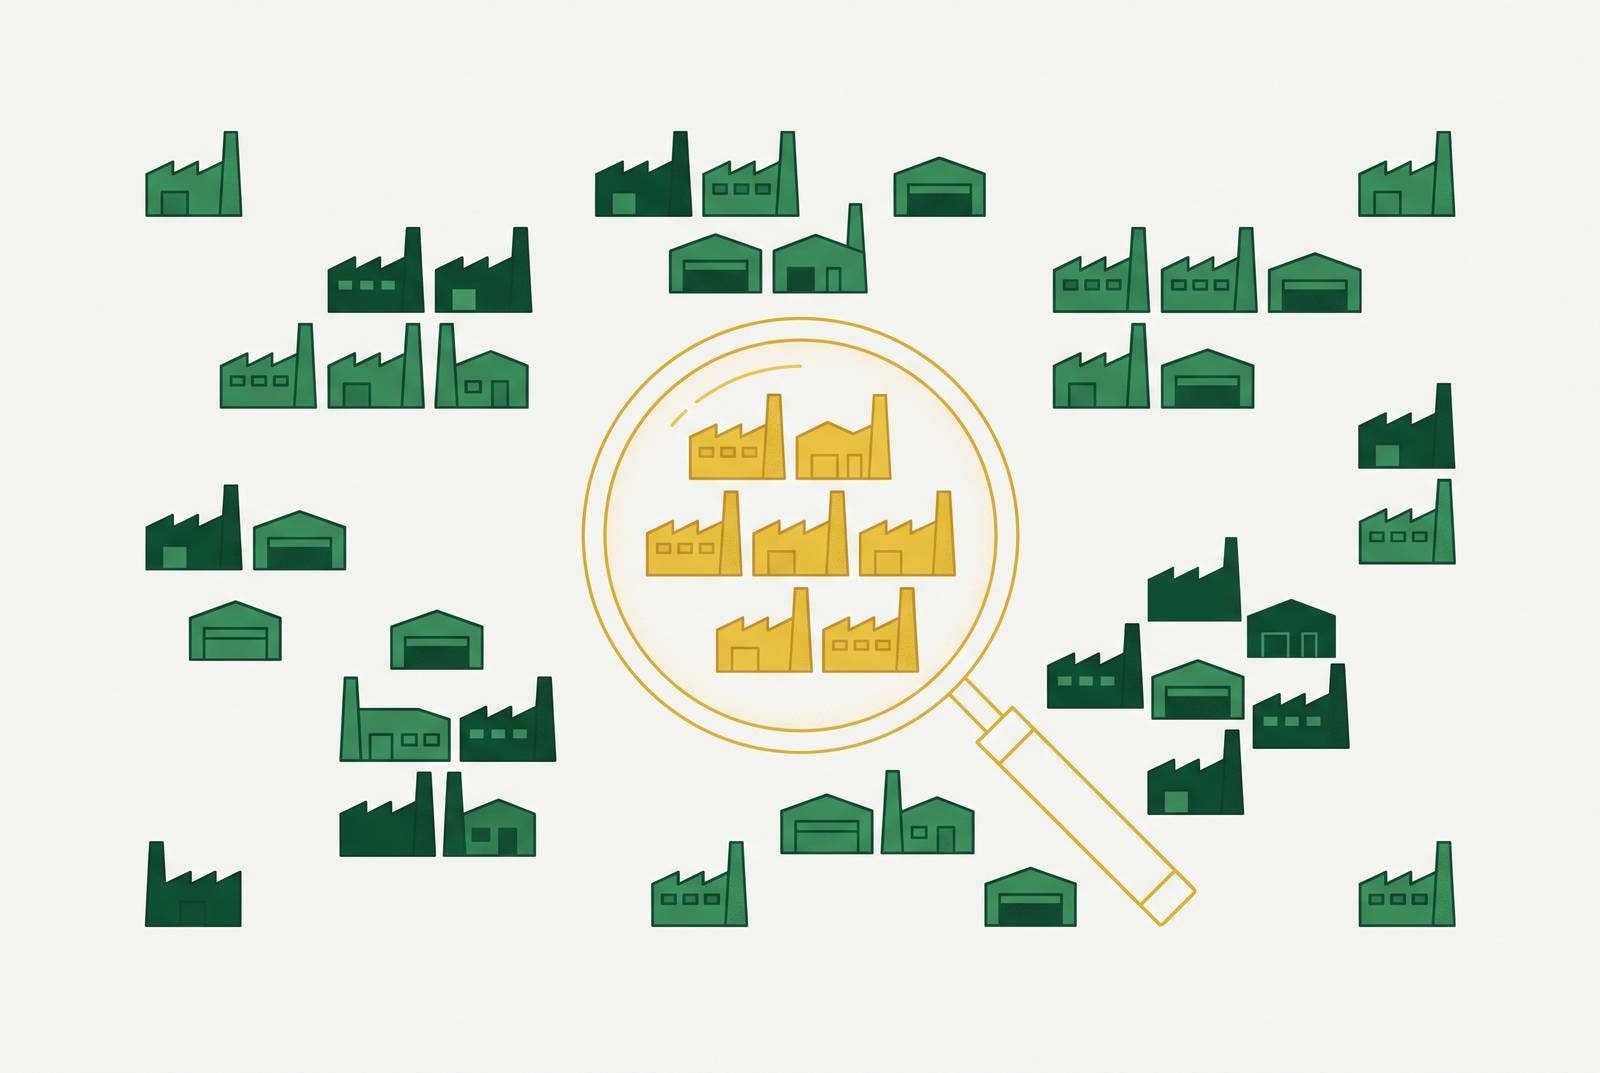
Most industrial territory plans treat mid-market manufacturers as filler between the named OEM accounts that actually matter. That assumption is wrong, and it's costing reps deals they never even see coming. Reshoring Initiative survey data shows that contract manufacturers under $25 million in annual revenue collectively account for 20% or more of U.S. manufacturing output. When territories get drawn by zip code or SIC bucket, treating multiple similar facilities sitting in the same industrial corridor as scattered, unrelated accounts obscures what they actually are: a demand pocket. By the time most reps make first contact, a competitor with better facility-level data has already locked in preferred-vendor status.
How manufacturing clusters form and where new ones are emerging
Clusters form because concentration beats dispersion. A region that builds a deep workforce pipeline, a tight supplier network, and shared infrastructure around one industrial base will outperform a region that spreads the same investment thin across unrelated sectors. This isn't a hunch, it's how regional economic development actually works when it's done well. A national government's Economic Development Administration's Build Back Better Regional Challenge put $1 billion into 21 clusters and generated $2.2 billion in private investment, more than 1,300 high-wage jobs, engagement from over 11,000 businesses, and 275 new companies. That's what organized cluster formation compounds into.
The geography is shifting fast. New manufacturing activity is concentrating in regions that would have seemed unlikely a decade ago, while established industrial heartlands continue anchoring legacy sectors. Texas, South Carolina, and Mississippi rank among the top 2025 reshoring and foreign direct investment states per the Reshoring Initiative, none of which fit the old idea of a manufacturing belt. The sectors driving this tend to be high-tech and medium-high-tech, with precision manufacturing, electrification-related equipment, and transportation equipment among the most active categories in recent reshoring data.
What do these new clusters actually look like from the ground? Highly automated plants, smaller but more skilled crews, and a lot of precision equipment, PLCs and CNC machines especially. Each of those details tells a rep something concrete to act on. Cluster formation moves faster than the review cycle does, which should worry anyone running an annual territory review. A corridor that had three or four qualified facilities eighteen months ago might have a dozen now, and nobody's territory map has caught up.
What plant-level signals reveal that firmographic data cannot
Firmographic data confirms a company exists and gives a rough headcount. It says nothing about what a specific facility makes, what process runs on its floor, or what that process actually consumes. That gap is where most industrial sales teams lose the account before they ever pick up the phone.
Process type matters first. Batch processing and continuous flow operations call for different chemistries, different fluids, different maintenance cycles, and a pitch built on the wrong assumption dies in the first five minutes. Equipment profile matters next: a facility dense with CNC machines has a predictable metalworking fluid demand, and aging equipment signals a replacement cycle that's either already open or about to be. Production volume and capacity utilization tell a rep whether a plant is growing, holding steady, or contracting, and each of those states calls for a different sales motion.
Environmental filings deserve particular attention. Chemical purchases often track directly against EPA consent decrees or OSHA deadlines, so EPA records reveal compliance obligations that create real, time-bounded purchasing windows. Hiring data works the same way, just earlier in the cycle: a facility posting for process engineers, quality managers, or EHS specialists is telegraphing strategic priorities before it commits capital. A plant hiring a sustainability manager is very likely shopping for green chemistry solutions, whether or not that's written anywhere public yet.
Construction permits and expansion announcements are the clearest purchasing trigger of all, because they precede equipment buying cycles that precede vendor selection. And this points to the real problem with timing: specs get written before vendors are formally contacted. The rep who shows up during specification gets to shape the evaluation criteria. The rep who shows up after is negotiating terms someone else already wrote to favor an incumbent. AI-assisted facility mapping, pulling from EPA filings, press releases, and public disclosures, now makes it possible to screen hundreds of sites for these signals before a single call gets made.
Why standard territory design fails to surface these clusters
Most industrial territory maps run on two inputs: geography (state, zip code, drive radius) and company-level firmographics (NAICS code, headcount, revenue band). Both inputs average away exactly the facility-level variation that shows whether real demand exists.
Then there's the fact that annual reviews fall out of date. A map set in Q4 reflects the market as it looked during planning season, and any cluster that formed or shifted during the year stays invisible until the next cycle runs, by which point a competitor may already be sitting inside it. Harvard Business Review research shows optimized territory planning can lift revenue 2 to 7% without adding a single rep, yet most organizations still run static annual maps built on geography and gut feel. Industry data shows the vast majority of sales teams missed 80% or more of their quota targets in 2024, a gap too systemic to blame entirely on rep performance.
Part of the problem is structural mixing. When one territory forces a rep to chase large OEM pursuits, twelve to twenty-four month cycles, multi-stakeholder buying committees, alongside faster mid-market cluster prospecting, the rep defaults to the named account every time. The cluster sits untouched because nobody has the bandwidth once the enterprise deal eats the calendar. White space gets acknowledged in nearly every sales kickoff deck and operationalized in almost none of them, because spotting a low-competition zone requires facility-density data that standard CRM and mapping tools simply don't carry.
Building a territory framework that exposes manufacturing cluster density
Fixing this starts with a three-layer data model. Layer one is internal: CRM win rates broken out by facility type and vertical, average contract value by process segment, and sales cycle length by account tier. This is where a team learns where it already has product-market fit at the plant level, not just the company level.
Layer two is geospatial, and it needs to go further than pins on a map. A 60-minute drive through a rural industrial corridor covers completely different ground than a 60-minute drive across a metro area, so density metrics matter more than raw counts, and isochrone (drive-time) mapping beats arbitrary radius circles. Layer three is third-party facility intelligence: production profiles, equipment types, environmental filings, expansion signals, and competitive presence at the plant level. This layer makes a cluster visible instead of just theoretical.
Account tiering needs to adapt too. Facilities with high revenue, complex buying committees, and long cycles fall into Tier 1, worth active management but not worth consuming all available capacity. Tier 2 is the cluster core: strong product-fit facilities with real upsell or cross-sell room. Tier 3 covers stable accounts that just need efficient renewal coverage, and a prospect tier tracks qualified facilities with measurable conversion odds based on process fit and signal activity.
Overlaying construction permits and expansion announcements against current account coverage exposes the corridors where a competitor is winning simply because nobody else showed up. And there's a strong argument for structuring by vertical rather than pure geography: a rep who carries real domain knowledge of one process type, metalworking, batch chemical, food-grade, builds credibility faster, asks sharper questions, and closes faster. Alexander Group data puts the productivity gain from territory optimization at 10 to 20%, which is the compounding payoff of closing coverage gaps and cutting the context-switching that comes from juggling unrelated verticals. Done right, this framework produces a short, prioritized list of cluster corridors with facility counts, process types, and live signal activity that reps actually use after the first read.
How CRM data quality and enrichment determine whether cluster intelligence reaches the rep
None of the above matters if the data rotting in the CRM undercuts it. B2B contact and account data decays rapidly, and for manufacturing teams chasing a narrow, finite set of industrial buyers, that decay does outsized damage because there's no slack in the account list to absorb the loss.
Gartner puts the annual cost of poor data quality at $12.9 million for the average organization. Validity's research found more than three-quarters of CRM users have less than half their CRM data accurate, and companies lose significant deals because of it. On top of that, a single industrial rep managing a large portfolio can burn a substantial portion of the week on manual prospecting and CRM cleanup, hours that come straight out of actual selling time.
For manufacturing accounts specifically, enrichment needs to carry facility-level production profiles beyond a company-level NAICS code. It needs equipment and process type data mapped to the rep's actual product line, expansion and hiring signals refreshed continuously rather than once a year, and contacts across plant operations, procurement, and EHS, not one name in a spreadsheet. There's also a gap between ERP and CRM that rarely gets closed: order volume changes, service ticket spikes on aging equipment, and credit indicators sit inside ERP systems and never reach the sales team, so reps miss churn and upsell signals that already exist somewhere in the business.
Enrichment that doesn't plug directly into the CRM a rep already uses, HubSpot, Salesforce, Dynamics 365, just becomes one more tab nobody opens. The intelligence has to show up inside the workflow, not next to it. Platforms that natively link sales and production data avoid the disconnect that appears when separate tools get stitched together after the fact, which matters specifically for manufacturing contexts.
Reading the cluster before a competitor does: timing the outreach
The highest-leverage moment in an industrial sales cycle sits before specification is finalized. Once a facility writes its spec, the evaluation criteria are set, and the rep who was in the room for that shapes the outcome. The rep who arrives after is stuck negotiating around someone else's language.
Signals arrive in a rough sequence, and reading them in order matters. Expansion announcements and construction permits come earliest, often well ahead of vendor selection. Regulatory filings, EPA consent decrees, OSHA deadlines, REACH registration windows, create urgent purchasing windows tied to fixed compliance dates. Strategic hiring for process engineers, EHS specialists, or sustainability managers signals capital investment priorities months before commitments are made. Equipment age and service ticket patterns point to consumable and replacement cycles that are often already underway.
Outreach anchored to one of these triggers, a specific permit filing, a named expansion, a compliance deadline, converts faster than a generic cold call, because it proves facility-level knowledge the prospect wasn't expecting from a vendor. As new corridors form in emerging reshoring buildout regions, the reps who show up early set the incumbent relationships before most competitors even recognize the corridor as worth working. Managers should be tracking what percentage of a cluster's facilities have actually been contacted, not raw call volume, and pipeline coverage should run well above quota with weekly prospecting minimums defined at the facility level. A single company can run several plants with completely different needs, so counting at the company level hides exactly the gap this whole framework is meant to close.
Turning a discovered cluster into sustained account growth
Winning one facility inside a tight industrial corridor is rarely just one deal. It's a reference point, because plant managers inside the same industrial park or supplier network talk to each other more than most sales teams assume.
Cross-sell inside existing manufacturing accounts stays badly underexplored. Most teams focus entirely on renewing the original product line and never chase the adjacent process needs sitting in the same building. Part of the reason is structural: a relationship that starts with procurement rarely surfaces the full range of plant-level needs, because procurement doesn't always know what plant operations, EHS, or quality management actually require. Research consistently shows that engaging multiple buying committee members through enriched outreach improves win rates, and the same logic extends outward: deepening stakeholder coverage in one facility builds the case for the next facility in the same cluster.
ERP signal monitoring should feed retention. Order volume declines, service ticket spikes, aging equipment data, all of it already exists somewhere in internal systems, and routing it to account managers means catching the churn risk or upsell window before a competitor does. As a cluster matures, some corridors get overworked while adjacent ones sit untouched, and continuous signal monitoring lets sales ops rebalance before reps burn out chasing a saturated patch or a live opportunity goes cold from neglect.
The pattern compounds when it's followed all the way through: a cluster caught early, entered on the strength of a real signal instead of a cold list, deepened through wider buying committee engagement, and sustained by ERP data feeding the account team. That's the territory that keeps performing without another headcount line added to the budget, which is the exact outcome optimized territory design promises and rarely delivers on its own.